Fuel Price Report: Diesel at $6.18 as Wholesale Diesel Falls 29 Cents in a Week
The national diesel average slipped 2 cents but is still $2.51 above a year ago. Diesel now costs $1.71 more per gallon than gasoline, and that gap is where fleet budgets are breaking.
Retail prices as of Oct. 12 · Wholesale as of Oct. 6 · Brent as of Oct. 6 · Alternative fuels for April 2026
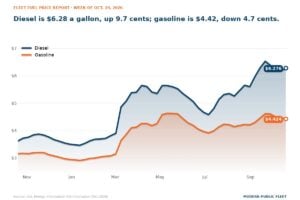
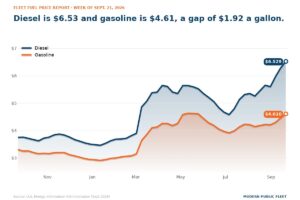
- Diesel: $6.18 a gallon, down 2 cents on the week, up $2.51 from a year ago, a rise of 69%. That is 35 cents below this year’s high of $6.53.
- Gasoline: $4.47, down about 3 cents and up $1.28 from a year ago. Diesel is $1.71 above gasoline, against a 47-cent gap a year ago.
- Regions: California diesel is $8.09 and the Lower Atlantic is $5.65, a $2.45 spread. The Rocky Mountain region was the only one where both fuels rose.
- Bulk buyers: New York Harbor wholesale diesel was $4.71 on Oct. 6, down 29 cents on the week, while the pump average fell 2 cents. The pump sits $1.47 above wholesale.
- CNG and propane: in DOE’s April report CNG was $3.48 per diesel-gallon equivalent against diesel at $5.55 in that same report, and propane was $5.53, within 2 cents of diesel on an energy basis.
- Why: Brent crude was $125.44 a barrel on Oct. 6, up $11.48 on the week. Over 12 months wholesale diesel is up 105% against crude up 87%, so the refiner’s margin on diesel has widened.
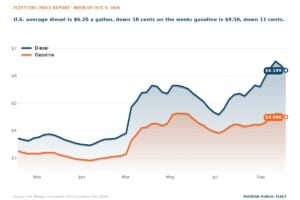
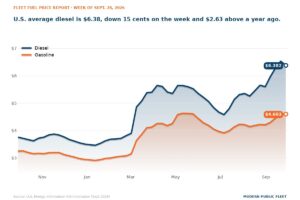
The U.S. average price of diesel was $6.179 a gallon in the week ending Oct. 12, EIA said, down 2 cents from the week before. Gasoline averaged $4.471, down about 3 cents. Diesel is $2.51 higher than a year ago, a rise of 69%, and sits 35 cents under this year’s high of $6.53. The year-to-date average is $5.07. Diesel also costs $1.71 more per gallon than gasoline. A year ago that gap was 47 cents, so a diesel-heavy fleet is carrying a penalty roughly four times the size it was last October.
On the cause, the evidence is thinner than usual. EIA discontinued the Highlights summary of its Weekly Petroleum Status Report effective Sept. 23, 2026, and points users to its weekly data tables instead, and EIA’s Short-Term Energy Outlook overview was unavailable when this report was written. What the price data do show: Brent crude, the world oil price that U.S. fuel prices follow, was $125.44 a barrel on Oct. 6, up $11.48 on the week, while the New York Harbor wholesale diesel price fell 29 cents over the same period.
Why it’s diesel that hurts
Diesel hurts more than gasoline because the fuel has been priced at a premium to crude for most of a year. Over 12 months the New York Harbor wholesale diesel price, the benchmark traders quote for barges in the New York area, is up 105%, while Brent is up 87%. Wholesale diesel has outrun crude, which is another way of saying the refiner’s margin on diesel, the gap between what a barrel of crude costs and what the finished fuel sells for, has widened. The six-month window is sharper still: Brent is down 9.2%, yet wholesale diesel is up 8.1% and pump diesel is up 10%.
What this report cannot tell you this week is what stockpiles are doing. With the weekly Highlights summary discontinued on Sept. 23 and the Short-Term Energy Outlook overview unavailable, there is no EIA stockpile figure, refinery utilization figure or forecast to quote here. The percentages above are price history, not a supply forecast. Readers who need the underlying inventory numbers can pull them from EIA’s weekly supply tables.
If you are building the last 11 weeks of the year on this year’s average, add $1.11 a gallon. EIA’s year-to-date diesel average is $5.07 and today’s average is $6.18. The difference is $1.11 a gallon, or $1,110 for every 1,000 gallons you still expect to burn before Dec. 31.
If you carry a fuel contingency line, size it against a 96-cent week. The largest one-week rise in the national diesel average over the past 52 weeks was 96 cents. Prices fell 2 cents this week, but a single week has moved that far within the past year, and a contingency built on a 10-cent assumption would not have covered it.
Where it hurts most
Diesel is above $6 in six of the eight regions EIA tracks. California is the outlier at $8.09, up 1 cent. The rest of the West Coast is $6.50, up 1 cent; the Central Atlantic, the New York to Virginia corridor, is $6.47, down 1 cent; New England is $6.44, down 4 cents; the Rocky Mountain region is $6.30, up 4 cents; and the Midwest is $6.26, down 3 cents. The cheapest diesel is in the Lower Atlantic, the Carolinas through Florida, at $5.65, down 5 cents, and on the Gulf Coast at $5.81, down 1 cent. California to the Lower Atlantic is a $2.45 spread.
Gasoline fell almost everywhere. California dropped 12 cents to $6.22, the largest move in either fuel this week. The Gulf Coast is the only region under $4, at $3.95, down 6 cents. New England fell 5 cents to $4.43, the rest of the West Coast 4 cents to $5.18 and the Lower Atlantic 3 cents to $4.04. Two regions went the other way: the Midwest, up 4 cents to $4.24, and the Rocky Mountain region, up 2 cents to $4.58.
What bulk buyers are paying
The pump average is $1.47 above the New York Harbor wholesale diesel price, which was $4.71 on Oct. 6, down 29 cents on the week. That $1.47 covers federal and state taxes, freight, the rack price that fleets load trucks at and the retailer’s margin. A fleet buying under a contract tied to a wholesale index avoids the retail piece and sees a fall like last week’s within days rather than weeks. The trade-off is that the same clause passes increases through just as fast. Separately, wholesale propane at Mont Belvieu, Texas, the main U.S. propane trading hub, printed 91.9 cents a gallon on Oct. 6. That is a wholesale number and is not comparable with any retail price.
If your contract prices off a wholesale index, check whether last week’s 29-cent fall has reached your invoice. New York Harbor wholesale diesel was $4.71 on Oct. 6, down 29 cents in a week, while the pump average moved only 2 cents. Index-linked gallons should show most of that quickly, and the lag in your own contract is worth timing now, while it is working in your favor.
If most of your fuel moves on cards, you are paying the full $1.47 retail spread. The pump average sits $1.47 above the New York Harbor wholesale print. Card fuel buys off-route coverage and audit trails, which have real value. It is still worth counting how many gallons genuinely need it against what you could load at your own tank, if you have tank capacity.
The trend: 3, 6 and 9 months
Read the four windows together. Diesel is up 29% over three months, 10% over six, 79% over nine and 67% over 12, so most of the damage was done last winter rather than this summer. Gasoline has the same shape at a smaller scale: up 12%, 5.1%, 54% and 37%. Wholesale diesel is the most violent line, up 40% over three months, 8.1% over six, 124% over nine and 105% over 12. Brent is up 75% over three months and 87% over 12, but down 9.2% over six. Crude and diesel have not moved together this year, and that divergence is the fleet’s problem.
CNG, propane and the other fuels
DOE’s Alternative Fuel Price Report for April 2026 is the latest available. Every figure here is per diesel-gallon equivalent, the amount of fuel that does the work of one gallon of diesel, and every comparison is with the diesel and gasoline in that same April report. CNG was $3.48 against diesel at $5.55, a gap of $2.07. Propane was $5.53, within 2 cents of that diesel figure, so at retail propane is level with diesel on an energy basis and any saving has to come out of a supply contract. LNG was $4.81. B20 was $5.41 and B99/B100 $5.80. E85 was $4.86 against gasoline at $4.63.
If CNG is on your capital plan, price your own station economics against the April spread rather than a national average. In DOE’s April report CNG was $2.07 per diesel-gallon equivalent below diesel nationally, and the regional gaps in that same report ran from $1.00 in New England, where CNG was $4.55 against diesel at $5.55, to $3.43 on the West Coast, where CNG was $3.73 against diesel at $7.16. That spread excludes station capital and maintenance, and it is April data, so your own quote is the number that decides it.
If you already run propane, the figure to work on is your supply contract, not the retail price. In DOE’s April report retail propane was $5.53 per diesel-gallon equivalent against diesel at $5.55, a difference of 2 cents. On an energy basis retail propane and retail diesel were effectively level in that month, which is why contracted gallons, not pump gallons, are where propane fleets find a saving. Worth pricing your current contract against that benchmark.
What to watch this week, and what it tells you
-
Every weekdayThe New York Harbor wholesale diesel print
It was $4.71 on Oct. 6 after a 29-cent weekly fall. If it holds or falls further, pump prices should follow within a week or two. If it bounces back toward $5, this week’s small pump decline will not last.
-
Monday, 5 p.m. ETEIA’s weekly retail prices for diesel and gasoline
Watch whether the national diesel average extends the 2-cent decline or turns back toward this year’s $6.53 high. The California and Lower Atlantic numbers set the $2.45 regional spread.
-
Wednesday, 10:30 a.m. ETEIA’s Weekly Petroleum Status Report data tables
The Highlights summary was discontinued effective Sept. 23, 2026, so the stockpile and refinery figures now have to be read from the tables at eia.gov/petroleum/supply/weekly. They are the supply check this report could not carry this week.
-
November, on the date EIA setsThe monthly Short-Term Energy Outlook
This month’s overview text was unavailable at publication, so there is no EIA diesel forecast in this report. The next edition is the first chance to see whether EIA expects the diesel premium over gasoline to narrow.
Glossary: how to read fuel prices
This note runs with every Fleet Fuel Price Report because these prices measure different things, and a buying decision made off the wrong one is expensive.
- Retail
- The pump price. EIA surveys stations every Monday. It includes federal and state taxes, freight to the station and the retailer’s margin, and it lags the wholesale market by one to two weeks. It is what a fleet pays on a fuel card, and it is the number most news reports quote.
- Wholesale, or spot
- Today’s price for a large lot of fuel at a trading hub: New York Harbor, the Gulf Coast or Los Angeles. EIA publishes it every business day. Rack prices and most supply contracts are set off it, and it is the earliest public signal of where the pump is heading.
- Futures
- A price agreed today for delivery in a future month, traded on the New York Mercantile Exchange. The nearest month tracks spot. The useful part is the shape of the curve: when later months are cheaper than the front month, the market expects today’s tightness to ease; when later months cost more, it expects the opposite. A fleet does not buy futures, but a fixed-price or capped supply contract is priced off them, so the curve is what your supplier is looking at when it quotes one. Futures settlements are published by CME Group and are not free to republish, which is why they are described here rather than charted.
- Bulk
- What a fleet pays a supplier for delivery to its own tanks. It is usually a published rack price, most often OPIS, plus or minus a differential and freight, or spot plus a differential. It excludes station margin, and for state and local governments it usually excludes the 24.4-cent federal excise tax on diesel and the 18.4-cent tax on gasoline, along with state fuel tax where the state exempts government use. Rack prices are proprietary, so there is no public bulk series. The gap between spot and retail is the closest public measure of what a bulk buyer avoids.
- Brent crude
- The price of a barrel of oil from the North Sea, used worldwide as the reference price for crude. Diesel and gasoline are made from crude, so when Brent moves, wholesale fuel follows within days and the pump within weeks. It is quoted in dollars per barrel; a barrel is 42 gallons.
- Energy-equivalent prices
- A gallon of propane, E85 or CNG does not hold a gallon of diesel’s energy, so DOE also states alternative fuel prices per gasoline-gallon equivalent (GGE) and per diesel-gallon equivalent (DGE). That is the price of the same amount of work, and it is the only fair way to compare a CNG or propane quote with a diesel one. The alternative fuels chart in this report uses it.
- What it means for buyers
- Watch spot for direction: a rising spot price this week is a higher pump price next week, and vice versa. Use the curve for planning: when later months are much cheaper, locking in long at today’s price is expensive insurance; when the curve is flat or rising, a fixed-price contract costs less to get. And judge any supplier quote against spot plus freight, never against the pump.
Source: U.S. Energy Information Administration (Oct 2026), Gasoline and Diesel Fuel Update, Spot Prices, Weekly Petroleum Status Report and Short-Term Energy Outlook; U.S. Department of Energy, Alternative Fuel Price Report (April 2026); IRS Publication 510. EIA and DOE data are U.S. government works in the public domain. Charts by Modern Public Fleet from those sources.